Financing Your Move
More Paths to 8574 Mountainview Ave Than You Might Think.
$499,900, and likely more ways to get there than you'd expect — VA, USDA, FHA, conventional, a much larger down payment, or all-cash. Explore the programs below, then try the calculator to see what a payment could look like.
A note on the numbers below: This page is educational only. Chuck Cornwell and CHC Realty are a licensed Virginia real estate brokerage — not a mortgage lender, loan originator, or broker — and nothing here is an advertisement, offer, or commitment to extend credit. Lender information on this page is provided by Movement Mortgage, LLC (NMLS ID #39179) and Allen Tardiff (NMLS #510000), is educational only, and is not a commitment to lend. Buyers may use any lender of their choice. Every figure is a hypothetical illustration based on the assumptions you choose, not a quote, pre-approval, or Loan Estimate. Actual rates, APR, program eligibility, and payments are determined by a licensed mortgage lender and change daily. Equal Housing Opportunity.
Explore Your Options
A Program for Nearly Every Buyer.
Every buyer's situation is different. These are some of the more common paths worth discussing with a licensed lender — not an exhaustive list, and not a recommendation of any one program.
VA Loan
Eligible active-duty service members, veterans, and qualifying surviving spouses.
- No down payment required for most eligible borrowers
- No monthly private mortgage insurance (PMI)
- A funding fee typically applies and is usually financed into the loan — it may be reduced or waived for veterans with a qualifying service-connected disability
USDA Rural Development Loan
Backed by the USDA for eligible rural and suburban properties, with income limits based on household size and county.
- No down payment required for eligible buyers
- A low annual guarantee fee replaces traditional PMI
- This address has not been confirmed as USDA-eligible — ask your lender to verify
FHA Loan
Popular with first-time buyers and buyers building or rebuilding credit.
- Down payment as low as 3.5% (10% down for credit scores in the 500–579 range)
- More flexible qualifying guidelines than many conventional programs
- Requires an upfront and annual mortgage insurance premium (MIP)
Conventional Loan
Widely used by buyers with solid credit and some savings for a down payment.
- Some programs allow as little as 3% down for qualifying first-time buyers
- PMI applies below 20% down and can typically be removed once you reach roughly 20% equity
- No government funding fee
Conventional — 20% Down
A traditional path for buyers with an existing home to sell or strong savings.
- No monthly mortgage insurance
- Often the most competitive pricing available
- A strong, straightforward offer in a competitive negotiation
Substantial Down Payment
Buyers bringing significant proceeds from a prior sale, investment funds, or other assets.
- Finance only the remaining half (or less) of the purchase price
- Smaller loan amount and smaller monthly payment
- No mortgage insurance, and a compelling position in negotiations
All-Cash Purchase
Buyers who prefer to close without a loan, contingency, or lender timeline.
- Often the strongest possible offer a seller can receive
- Simpler, faster closing process
- Still worth a conversation with a lender — a cash-out refinance later is always an option
Side-by-Side
Quick Comparison.
| Program | Typical Min. Down | Ongoing MI / Fee | Best Fit For |
|---|---|---|---|
| VA | 0% | None (funding fee may apply, often financed) | Eligible veterans, active-duty & surviving spouses |
| USDA | 0% | Annual guarantee fee | Eligible rural homes, within income limits — eligibility for this address unconfirmed |
| FHA | 3.5% | Annual MIP | First-time buyers & buyers building credit |
| Conventional | As low as 3–5% | PMI if under 20% down (removable) | Buyers with solid credit & some savings |
| Conventional 20%+ | 20% or more | None | Buyers with strong savings or sale proceeds |
| Cash / Large Down | 50%–100% | None | Move-up buyers & buyers prioritizing a strong offer |
Program terms and fees are typical ranges, not guarantees — every lender and program differs, and details change over time.
Payment Calculator
What Could a Payment Look Like?
Adjust the purchase price, annual real estate tax, down payment, sample rate, and term to estimate a monthly payment including principal & interest, applicable PMI, taxes, and estimated homeowners insurance. The default purchase price is $499,900 — not a loan quote.
Default: $499,900 list/offered price.
2026 Fauquier County tax record — verify with county. Record tax: $3,953/yr; assessment: $429,700.
Estimated monthly payment
$3,793/mo
- Down payment
- $24,995 (5%)
- Loan amount
- $474,905
- Principal & interest
- $3,080/mo
- Est. mortgage insurance (PMI)
- $237/mo
- Real estate tax
- $329/mo
- Homeowners insurance — estimate
- $146/mo
Insurance is an automatic estimate: 0.35% of purchase price per year ($1,750/yr), not an insurance quote. Actual coverage and premiums vary.
Includes principal & interest, estimated PMI when applicable, annual real estate tax divided by 12, and estimated homeowners insurance. PMI uses an illustrative 0.60% of the loan per year below 20% down; actual mortgage insurance varies by loan program and borrower. This is a hypothetical illustration only — not a loan offer, quote, or Annual Percentage Rate (APR) disclosure, and not a commitment to lend. Your actual rate, APR, mortgage insurance, and payment will be provided by a licensed mortgage lender.
Illustrative rates reflect general market conditions and are provided only as a starting point for your own exploration. Mortgage rates change daily and vary by lender — this is not a rate quote or an Annual Percentage Rate (APR) disclosure under the federal Truth in Lending Act.
Your Lender
Why Movement Mortgage?
For rates, pre-approval, and the loan itself, the lender contact for this listing is Allen Tardiff at Movement Mortgage. Of course, you are always free to use any lender of your choice.
People-First Lending
Movement Mortgage approaches lending around the people taking out the loan — service built to fit the borrower, not the other way around.
A Fast, Transparent Process
Clear communication and a streamlined process from application to closing, so you always know where your loan stands.
Community Focus
Through the Movement Foundation, the company gives back to the communities it serves across the country.
Meet Your Local Loan Officer.
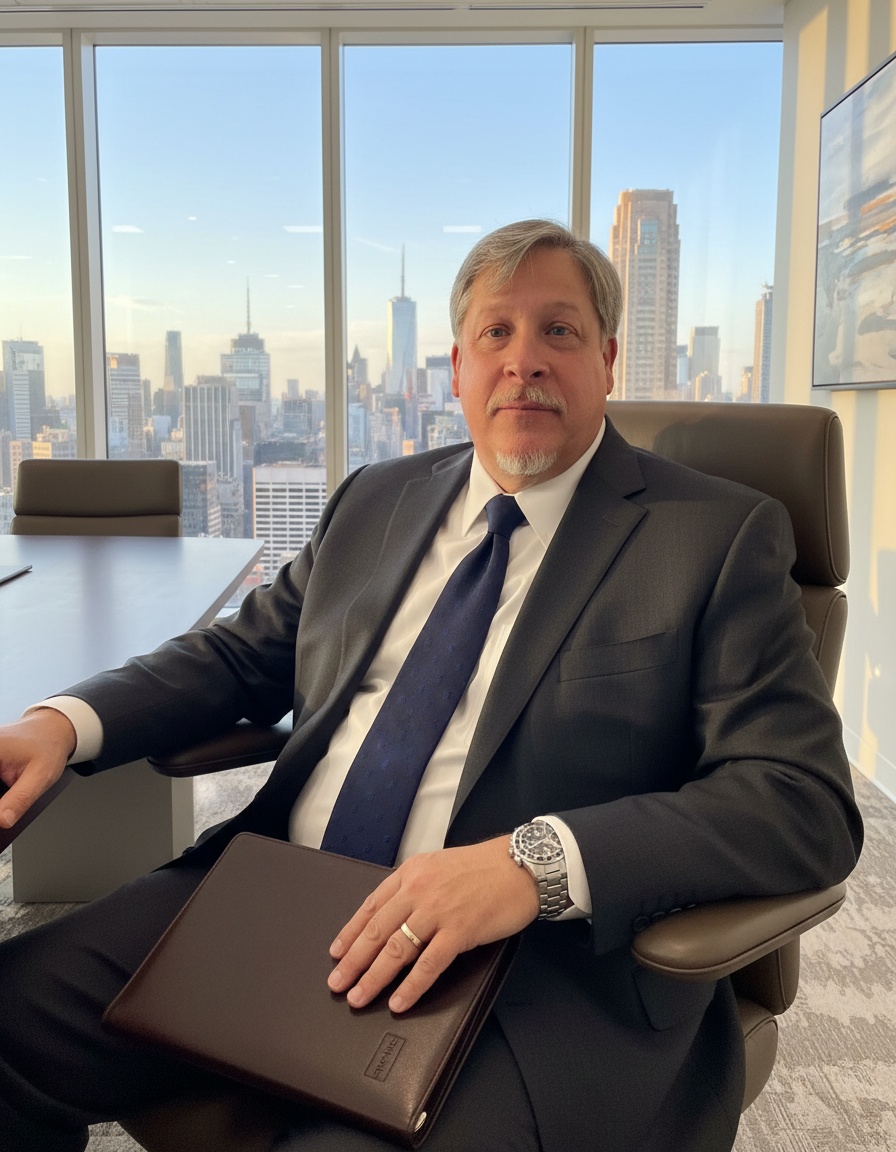
Allen Tardiff
Team Leader | Movement Mortgage
With over 33 years in the mortgage industry, the last 8 as a Team Leader at Movement Mortgage, Allen is dedicated to helping people achieve homeownership. He believes in educating his clients, operating with integrity, and keeping the process transparent from application to closing.
Start Here
Start Your Mortgage Application.
Ready to run real numbers on 8574 Mountainview Ave? Start your application with Allen online — it takes just a few minutes, and you can always reach him directly by phone or email.
Start Your Mortgage ApplicationContact Allen TardiffBorrowers may use any lender of their choice. Lender information here is provided by Movement Mortgage, LLC (NMLS ID #39179) and Allen Tardiff (NMLS #510000) — educational only, not a commitment to lend.
Ready to Run Real Numbers?
Start your application with Allen Tardiff at Movement Mortgage, or reach out to him directly. Questions about the property? Chuck Cornwell, CHC Realty — (540) 729-7801 or chuck@chuckcornwell.com.
Financing Disclosures
The financing information, loan program descriptions, and payment examples on this page are provided for general informational and illustrative purposes only. They do not constitute an advertisement, application, offer, or commitment to make a loan. CHC Realty and Chuck Cornwell are not mortgage lenders, loan originators, or mortgage brokers, and do not take loan applications, set interest rates, or guarantee financing approval, terms, or program eligibility.
Payment examples reflect the down payment, interest rate, loan term, and other assumptions selected using the interactive tool above. They are not an Annual Percentage Rate (APR) disclosure required under the federal Truth in Lending Act (Regulation Z) and do not include all costs of credit. Actual interest rates, APR, mortgage insurance, funding or guarantee fees, closing costs, and monthly payments will vary based on the buyer's credit profile, the lender selected, the specific loan program and its current guidelines, and market conditions at the time of application, and may differ materially from the examples shown. The calculator includes the annual real estate tax entered divided by 12, defaulting to $3,953 from the 2026 Fauquier County public tax record (assessment $429,700) — verify with county. Homeowners insurance is an automatic estimate of 0.35% of purchase price per year, not a quote; actual taxes, coverage, premiums, and mortgage insurance may differ. Closing costs and funding or guarantee fees are not included in the monthly total.
Lender information on this page is provided by Movement Mortgage, LLC, NMLS ID #39179, and Allen Tardiff, NMLS #510000. It is educational only and is not an advertisement for credit, an application, or a commitment to lend. Buyers may use any lender of their choice.
VA, USDA, FHA, and conventional loan program availability and eligibility — including any property or area eligibility for USDA financing, which has not been confirmed for this address — are determined by the applicable government agency, investor guidelines, and the buyer's individual qualifications, not by CHC Realty. Buyers are strongly encouraged to consult a licensed mortgage loan originator and obtain a written Loan Estimate before relying on any figure shown on this page, and to compare offers from more than one lender.
Equal Housing Opportunity. Under the Equal Credit Opportunity Act, it is illegal to discriminate in any aspect of a credit transaction based on race, color, religion, national origin, sex, marital status, age, receipt of public assistance income, or good-faith exercise of rights under the Consumer Credit Protection Act.